ABOUT THIS PRACTICE

About Natural Disasters

In the aftermath of a natural disaster, insurance companies deploy armies of adjusters and so-called independent experts with one unified goal: to minimize or completely deny your claim. They rely on deceptive delay tactics, blame catastrophic destruction on pre-existing wear and tear, and hide behind convoluted anti-concurrent causation clauses to protect their bottom line.
At Boyle Anderson, we know their playbook. We aggressively represent commercial property owners, condominium associations, general contractors, and developers who have suffered devastating losses from hurricanes, floods, and severe weather events. We do not accept lowball settlements or structural compromises. Because we spend every day litigating against major carriers, we know how to dismantle their defenses, expose bad faith practices, and secure the capital you need to rebuild.
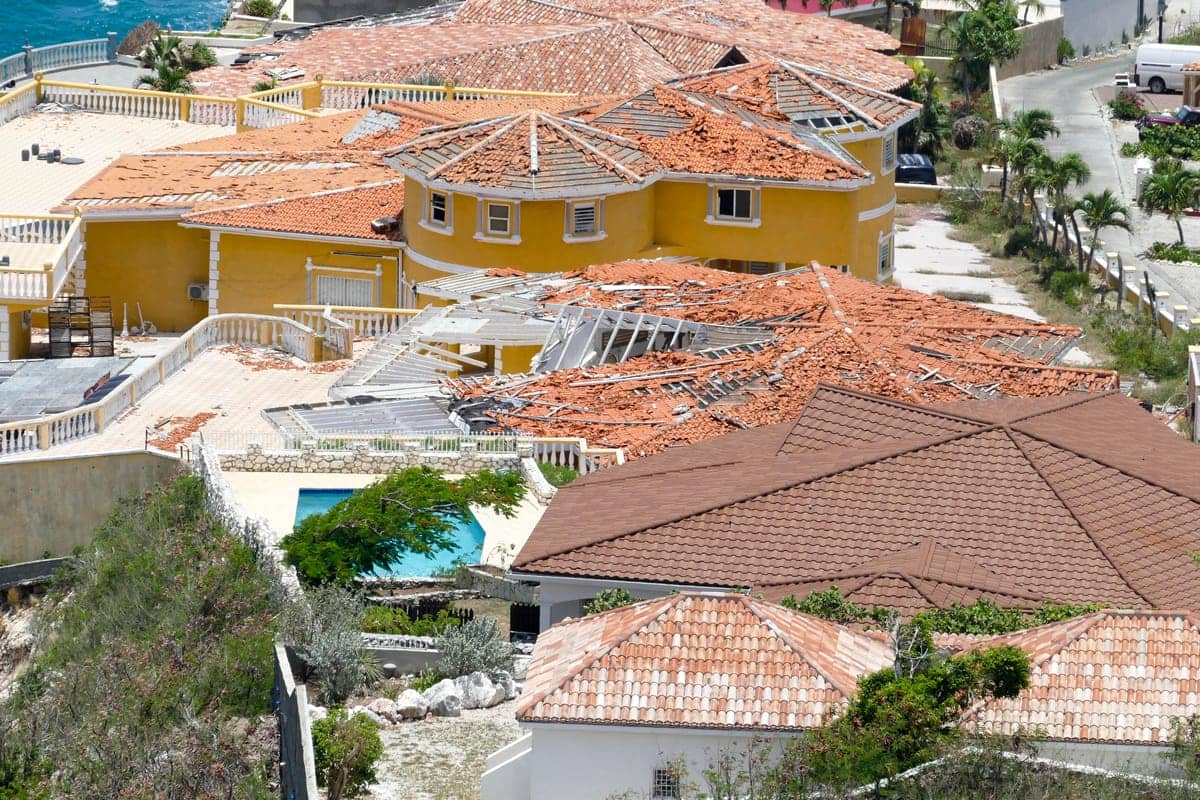
Aerial view of homes with roof damage after a hurricane
OUR GOAL
Maximize your recovery. We strip away the insurer’s excuses and leverage our extensive trial experience to secure full, fair, and prompt compensation for your catastrophic property damage and operational losses.
HOW WE HELP
How Our Team Can Assist You
When a hurricane or major storm hits, time is critical and the financial stakes are enormous. We step in immediately to take control of the claims process, shielding you from the insurer’s predatory adjustment tactics. From deploying our own independent structural engineers and meteorologists to meticulously documenting your losses, we build an airtight case from day one. If the insurance company attempts to act in bad faith—unreasonably delaying payments, under-scoping the damage, or wrongfully denying coverage—we take them to court and hold them financially accountable.
Tampa, Florida skyline seen across the river

Hurricane & Windstorm Damage

Insurers routinely attempt to underpay wind claims by disputing the severity of the damage, asserting faulty construction, or categorizing the loss under exorbitant named-storm deductibles. We fight back against these tactics, utilizing industry-leading experts to prove the true extent of wind-driven damage to roofs, building envelopes, and structural components to force a full payout.
We analyze complex CGL policies for businesses, developers, and contractors to ensure your operations are fully protected. We identify dangerous exclusions, verify appropriate coverage limits, and ensure your policy aligns perfectly with your specific industry risks and contractual obligations.
City skyscrapers at golden hour

Flood vs. Wind Causation Disputes

Following a major storm, adjusters often try to shift the blame entirely to storm surge or flood water to trigger devastating policy exclusions. We relentlessly challenge their biased causation reports, navigating the complex legal intersection of wind and water (the “anti-concurrent cause” doctrine) to ensure your covered windstorm perils are rightfully recognized and paid.
High-value properties and construction projects require ironclad protection. We review commercial property and builders risk policies to verify coverage for catastrophic events, business interruption, and construction delays, ensuring you aren’t left exposed by hidden sub-limits or restrictive definitions of a “covered loss.”
Attorney in a suit standing in an office lobby

Business Interruption & Extra Expense

A natural disaster doesn’t just damage physical buildings; it paralyzes your operations. We work with forensic accountants to calculate your true lost income, construction delays, and extra expenses incurred to keep your business alive. We aggressively pursue these claims, forcing insurers to honor their business interruption coverage so your company survives the downtime.
The true scope of your coverage is almost always buried in the fine print of endorsements. Our attorneys meticulously audit policy addendums and exclusions, translating dense legalese into plain English so you know exactly how an insurer might try to limit their liability during a high-stakes claim.
Aerial view of homes with roof damage after a hurricane